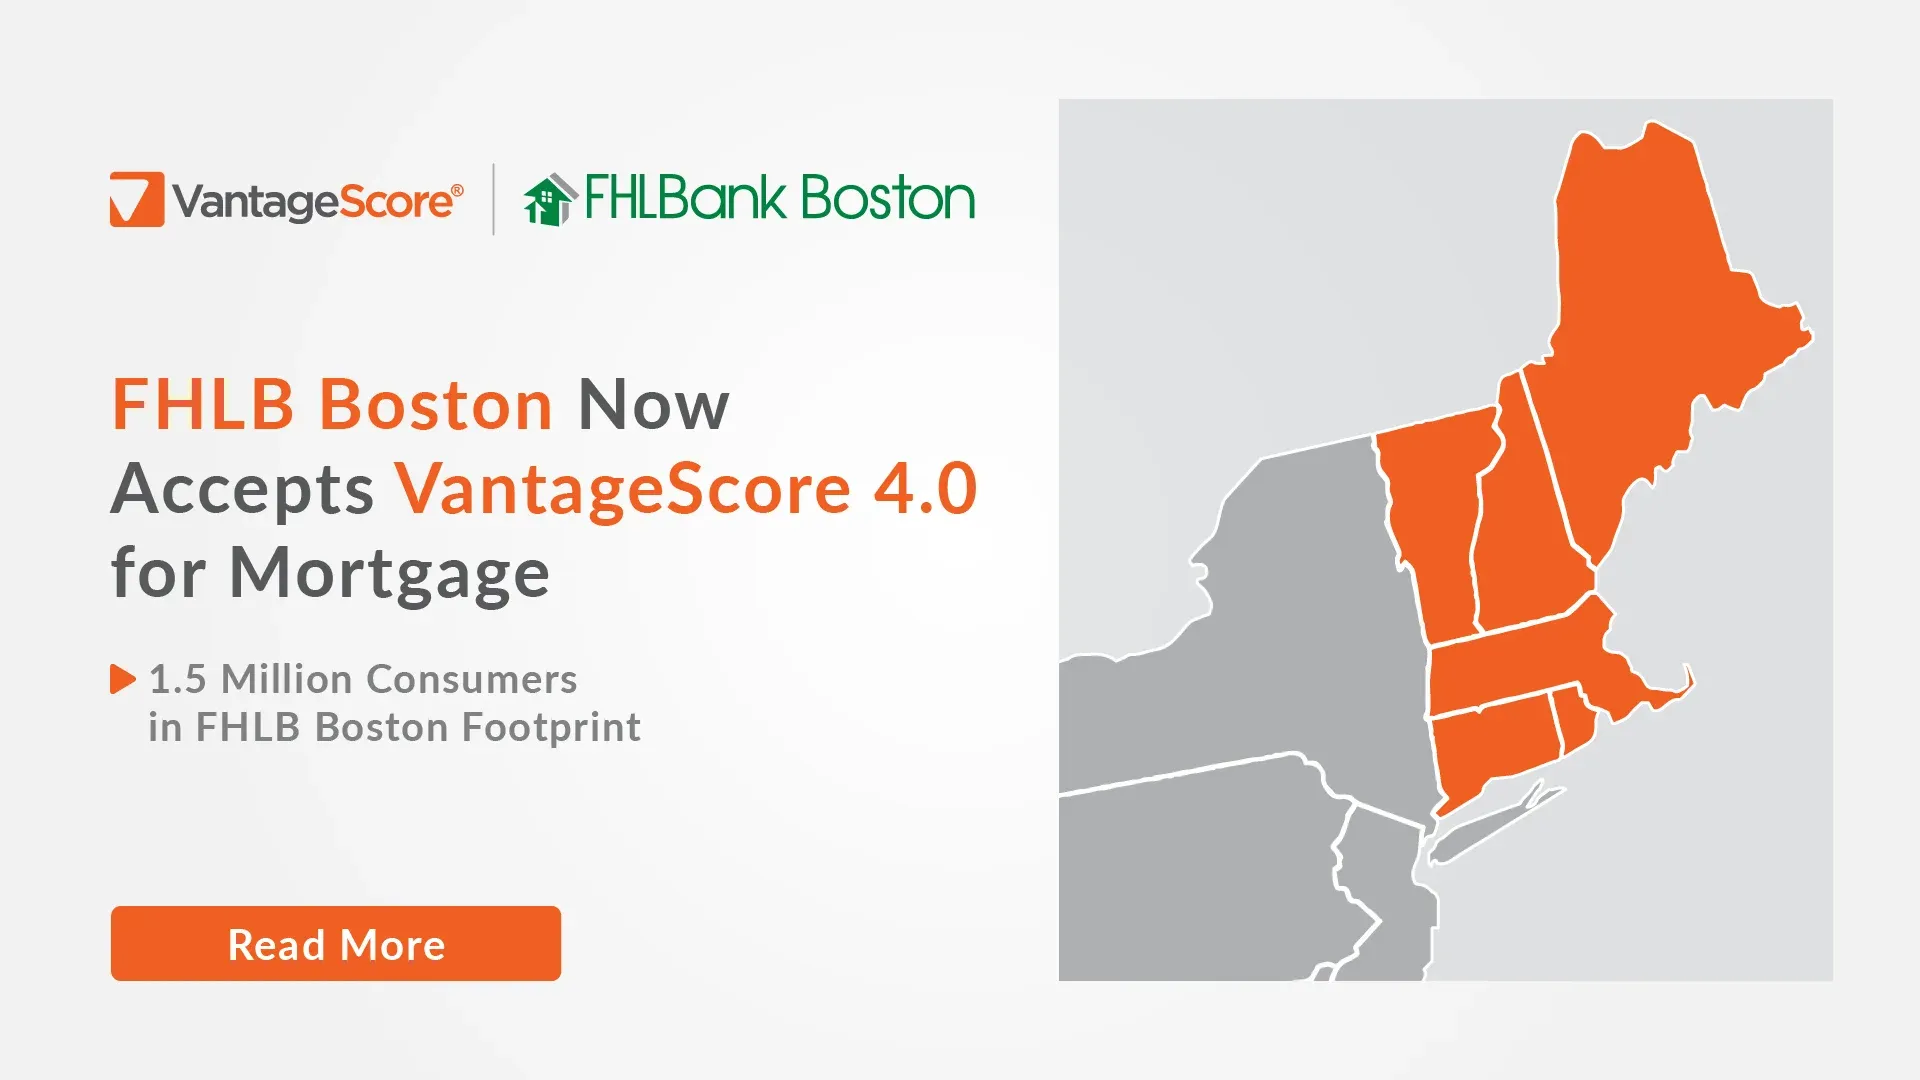
The Federal Home Loan Bank of Boston is expanding credit accessibility by allowing its member institutions to pledge mortgage collateral using the VantageScore 4.0 model. This immediate implementation enables over 400 member banks to utilize a scoring system that covers an estimated 1.5 million additional consumers across the New England region, potentially broadening local homeownership opportunities.
Expanding Credit Access via VantageScore 4.0
FHLBank Boston has authorized its members to use VantageScore 4.0 for mortgage collateral, a move that directly impacts the lending capacity of its 400+ member banks and institutions. This decision is expected to reach 1.5 million more consumers within the bank's specific footprint, which includes Connecticut, Maine, Massachusetts, New Hampshire, Rhode Island, and Vermont. By integrating this model, FHLBank Boston aims to provide lenders with more inclusive scoring capabilities. This shift aligns with broader industry trends, as VantageScore 4.0 is designed to score 33 million more people than traditional models, offering a wider lens for assessing mortgage-eligible borrowers.
Integration with Government-Sponsored Entities
FHLBank Boston joins a growing list of government-sponsored mortgage entities and agencies that have adopted the VantageScore 4.0 model. Key entities already accepting this model include Fannie Mae, Freddie Mac, the Federal Housing Administration, and the Department of Veterans Affairs. Other Federal Home Loan Banks, such as FHLB Chicago, Dallas, and New York, have also integrated the technology. This widespread adoption follows the Federal Housing Finance Agency (FHFA) allowing the immediate use of VantageScore 4.0 for Fannie Mae and Freddie Mac guaranteed mortgages, signaling a significant shift in the standardized infrastructure used for mortgage credit scoring across the United States.
Key Takeaways
- FHLBank Boston members can now pledge mortgage collateral using the VantageScore 4.0 model.
- The move is estimated to expand credit access to 1.5 million additional consumers in New England.
- FHLBank Boston joins major entities like Fannie Mae and Freddie Mac in accepting VantageScore 4.0.
FinanceInsyte's Take
In our view, FHLBank Boston’s adoption signals a critical momentum shift toward more inclusive credit scoring models within the mortgage collateral ecosystem. By moving beyond traditional models, the bank is providing its 400+ members with the tools to capture a larger segment of the New England market. This integration with major GSEs suggests that VantageScore 4.0 is rapidly becoming a standardized pillar of mortgage financial infrastructure, potentially altering how liquidity is managed for mortgage-backed assets.
Questions & Answers
How many additional consumers could benefit from this change in the New England region?
The adoption is expected to provide credit access to approximately 1.5 million more consumers within the FHLB Boston footprint, covering Connecticut, Maine, Massachusetts, New Hampshire, Rhode Island, and Vermont.
Which major mortgage entities have already adopted the VantageScore 4.0 model?
The model is already accepted by Fannie Mae, Freddie Mac, the Federal Housing Administration, the Department of Veterans Affairs, and several other FHLBs, including Chicago, Dallas, and New York.
What is the broader national impact of VantageScore 4.0 according to the company?
VantageScore estimates that the use of its 4.0 model will expand credit access to approximately 13 million more mortgage-eligible borrowers nationwide.
How does the VantageScore 4.0 model compare to traditional scoring models in terms of reach?
The VantageScore 4.0 credit scoring model is designed to score 33 million more people than traditional models, providing a broader data set for assessing creditworthiness.
Source: VantageScore