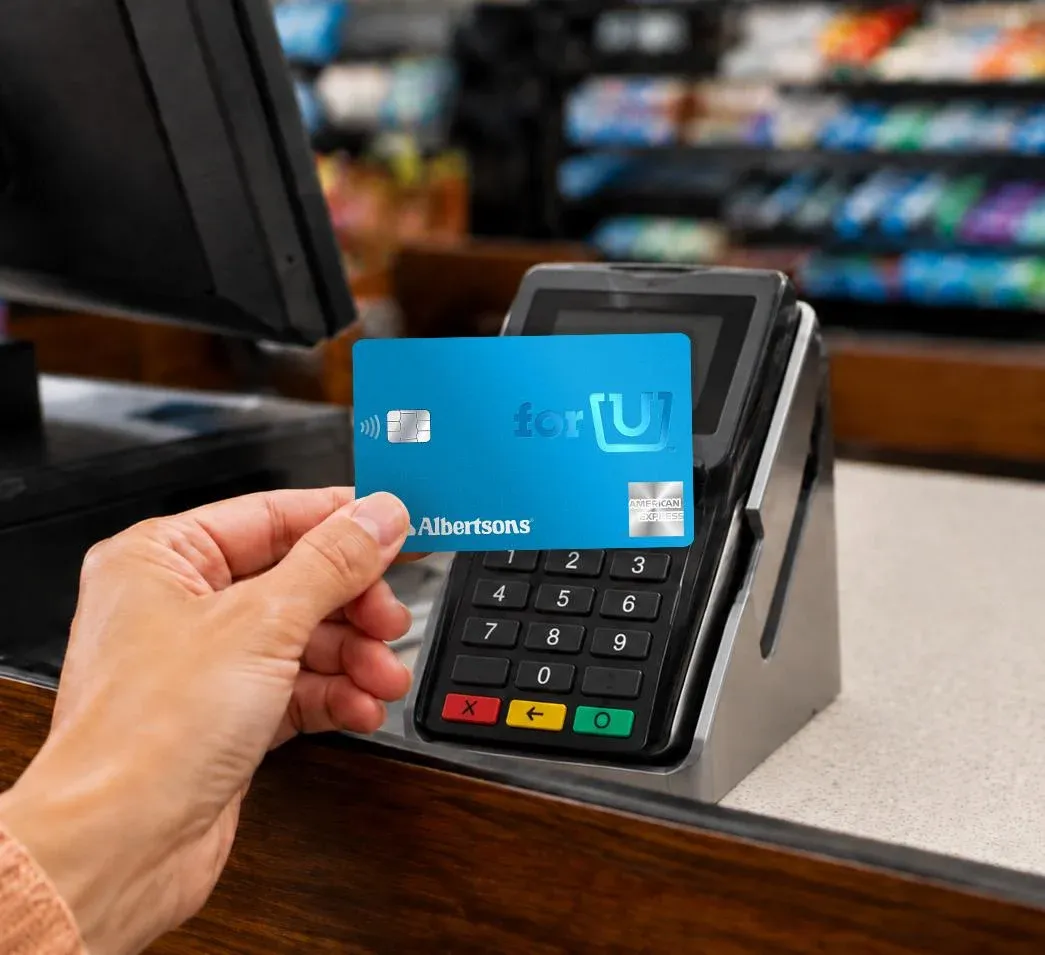
Albertsons Companies, Inc. (NYSE: ACI) is attempting to deepen consumer engagement and capture a larger share of daily wallet spend through a new strategic fintech partnership. By launching the Albertsons forU™ American Express® Card, the grocery giant is integrating its massive retail footprint with the American Express (NYSE: AXP) network and the Imprint payments platform. This move seeks to transform routine grocery, pharmacy, and fuel transactions into a structured loyalty ecosystem. The collaboration leverages Albertsons' 2,200+ stores and 1,709 in-store pharmacies to incentivize high-frequency spending via a tiered rewards structure that extends beyond the supermarket aisle into dining, utilities, and streaming services.
Albertsons forU™ Card Rewards and Structure
The new credit card, issued by First Electronic Bank, utilizes a multi-tiered reward system designed to incentivize both digital and physical commerce. For Albertsons Companies customers, the card offers 5% back on online and app-based purchases, including pickup and delivery services. In-store transactions, including pharmacy purchases such as prescriptions and immunizations, earn 3% back. Beyond the grocery ecosystem, the card provides 3% back on gas, dining, streaming services, and utilities, while all other eligible purchases earn 1% back.
To drive initial adoption, the partnership includes a welcome offer: new cardholders can earn a $50 statement credit after spending $1,000 on net purchases outside of Albertsons Companies stores within the first 90 days of account opening. Notably, the card carries no annual fee, a strategic choice likely intended to lower the barrier to entry for a broad consumer base. The product is powered by the Imprint payments, loyalty, and intelligence platform, which manages the digital customer experience, while the American Express Network provides access to Amex Offers and Amex Experiences™ for travel, dining, and entertainment.
Strategic Integration of Retail and Fintech Infrastructure
This launch represents a sophisticated convergence of traditional retail scale and modern fintech agility. Albertsons is positioning the card to capture value across its diverse brand portfolio, which includes Safeway, Jewel-Osco, Vons, ACME, Shaw’s, Star Market, Tom Thumb, Randalls, Haggen, United Supermarkets, and Pavilions. Each of these banners will feature a unique card design, yet the underlying financial utility remains unified through the American Express network.
By utilizing Imprint’s intelligence platform, Albertsons is moving toward a more data-driven approach to customer loyalty. Imprint’s role is to integrate earning, saving, and tracking into a single digital interface, allowing the retailer to bridge the gap between physical grocery shopping and digital financial management. This infrastructure allows Albertsons to leverage its existing trust with consumers—evidenced by its massive scale of 2,240 retail stores—to build a more comprehensive financial relationship. The inclusion of pharmacy and fuel center transactions into the rewards loop suggests a strategy to capture a wider variety of essential consumer spending categories, effectively turning a grocery loyalty program into a broader lifestyle financial tool.
Key Takeaways
- The Albertsons forU™ American Express® Card offers 5% back on online/app purchases and 3% back on in-store and pharmacy transactions at Albertsons Companies stores.
- Cardholders earn 3% back on gas, dining, streaming services, and utilities, with a $50 statement credit available after $1,000 in non-Albertsons spend within 90 days.
- The product is issued by First Electronic Bank and powered by the Imprint payments and loyalty platform, featuring no annual fee.
FinanceInsyte's Take
In our view, this partnership signals a significant shift in how large-scale retailers are approaching the "closed-loop" loyalty model. By partnering with American Express and Imprint, Albertsons is not merely offering a discount card; it is attempting to build a sophisticated financial layer atop its physical retail dominance. This move allows Albertsons to capture high-margin data on consumer spending habits across diverse categories like utilities and dining, which are traditionally difficult for grocers to track.
The decision to omit an annual fee suggests that the primary objective is volume and data acquisition rather than immediate fee income. By lowering the friction for entry, Albertsons is betting that the increased frequency of "top-of-wallet" usage will drive long-term customer lifetime value. For the fintech sector, this illustrates the growing trend of established retailers utilizing specialized platforms like Imprint to compete with traditional banking loyalty programs.
Questions & Answers
How does the reward structure differentiate between digital and physical Albertsons transactions?
The card provides a higher incentive for digital engagement, offering 5% back on online and app-based purchases (including pickup and delivery), whereas in-store and pharmacy transactions, such as prescriptions and immunizations, earn 3% back.
What are the specific requirements to trigger the $50 welcome statement credit?
To qualify for the $50 statement credit, new cardholders must make $1,000 in net purchases specifically outside of Albertsons Companies brands within the first 90 days of opening the account.
Which entities are responsible for the technical and financial execution of this card?
The card is issued by First Electronic Bank pursuant to a license from American Express, while the Imprint platform provides the payments, loyalty, and intelligence infrastructure to manage the digital customer experience.
Does the card offer benefits beyond the Albertsons retail ecosystem?
Yes. Because it is powered by the American Express Network, cardholders gain access to Amex Offers for shopping, dining, and travel, as well as Amex Experiences™ for event ticket presales and venue perks.
Source: American Express